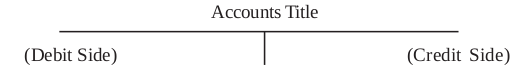Pages

Showing posts with label Book Keeping and Accountancy. Show all posts

Case Study on Product Costing in a Dairy Plant

A study was conducted in a dairy plant under the co-operative set-up in Erode district of Tamilnadu to estimate the cost of production of different products. The dairy plant is a feeder-balancing dairy. It collects milk from its own milk-shed area in Erode district. In addition to it, milk from other milk-producers co-operative unions and State Federations is diverted to this plant for conversion into milk and other dairy products. During the period April 99 to March 2000, 725 lakh litres of milk was received at the plant. Data on various aspects like milk inflow, raw materials consumed, expenses incurred in generation of utilities, manpower employed, products manufactured and other expenses for the financial year 1999-2000 were taken from the dairy plant. Process costing technique was applied to estimate cost of production of different products.The following criterion was adopted to allocate /apportion costs. 

Skim milk powder (SMP) was the highest contributor in revenue generation with 42.93 per cent share obtained from 477.5 tonnes of output. Butter and Ghee were other significant products accounting for 39.48 percent and 16.37 per cent of revenue respectively. Standardised milk, Dudh Peda, Flavoured milk and other products individually had less than 1 per cent share in total revenue. 

Product Mix of the Dairy Plant (1999-2000)
The cost of manufacture of different dairy products is displayed in Table


Cost of Manufacture of Various Dairy Products (1999-2000)
It could be easily seen that in all the products manufactured, the major item of cost was on account of raw materials followed by processing and packaging cost in that order. The cost of production of SMP worked out to be Rs.70.19 per Kg.The respective share of raw materials cost, processing cost and packaging cost in the total cost was 83.25 per cent, 15.36 per cent and 1.39 per cent.The average manufacturing cost of Butter was Rs.91.23 per Kg.. Manufacturing activities added cost to the extent of Rs.8.58 to the raw materials worth Rs.82.65.Packaging cost constituted one per cent of the total cost.The longer shelf-life and returns associated with Ghee manufacture has attracted many entrepreneurs, especially in Tamil Nadu to initiate dairy business with this product line .The average cost of Ghee was found to be Rs.113.05.The relative share in cost on account of raw materials processing and packaging was 87.92 per cent, 7.29 per cent and 4.79 per cent.

Standardized milk is not a major revenue-earning product of the plant. But to cater to the demand of the consumers, standardized milk is processed in the plant for sale in nearby towns. During the study period the plant processed 4,86,258 litres of standardized milk at an average cost of Rs.10.91 per litre. The cost on raw material, being 91.86 per cent of the total cost, was highest among all the products. The processing and packaging cost were 4.75 per cent and 3.39 per cent respectively.

Dudh Peda, a desiccated indigenous product is popular in the region. It commands high demand throughout the year. The plant manufactured 45700 Kg. of Dudh Peda during the period under consideration. The cost of production turned out to be Rs.47.41.Raw materials cost was Rs.30.67 (64.68%) followed by processing cost, Rs.12.60 (26.59%) and packaging cost of Rs.4.14 (8.73%)The cost of manufacture of different dairy products has been analyzed from other angle segregating total cost into fixed and variable costs. These costs are produced below


Cost of Production of Different Dairy Products (1999-2000)
 The above cost figures are indicative only and applicable to the case dairy plant.These cost figures may vary from plant to plant depending upon factors such as fixed costs on land and building, plant and machinery, equipments etc. Installed capacity and capacity utilized, input costs and productivity of the resources also have a strong bearing on the cost aspects and these factors should be taken into consideration while working out cost of manufacture of dairy products.(The case study is based on research work conducted by Mr. P.Murali in partialfulfilment for the award of Degree in Master in Science in Dairying (Dairy Economics) to the N.D. R.I. Deemed University, Karnal, Haryana).

Cost Measurement

Product costing is the process of tracking and studying all the various costs that are incurred by the firm on its products or we can say what it costs to make the product. To determine the total cost of a product you need to calculate both the direct and indirect costs. The total cost is the sum of all costs associated with a particular unit or process or department or batch. It comprises of cost of production, selling and distribution expenses. It is also called cost of sales.Product costs are traceable to the product and include direct material, direct labour and overheads. As already mentioned that for the purpose of formulating various strategies and policy matters, the total cost of the product must be ascertained. This means allocating the direct materials cost, direct labour cost, other direct expenses and allocation / apportionment of burden of manufacturing overheads, Office overheads and Selling and Distribution overheads to the product.

How product costing is accomplished in any manufacturing unit becomes easy if we understand what types of departments do we generally have in any organization. In a manufacturing concern there are generally two types of departments

i) Production Departments and
 
ii) Service Departments.

A production department is one that is engaged in the actual manufacture of the product by changing the shape, form or nature of material worked upon or by assembling the parts into finished product.. In a dairy plant or dairy factory, the departments which are manufacturing ghee, butter, ice cream, flavoured milk,lassi, milk of different grades like skim milk, double toned milk, toned milk,
standardized milk, full cream milk are production departments A service department, on the other hand, is one, which is rendering a service to production departments. It contributes in an indirect manner to the manufacture of the product but it does not itself change the shape, form or nature of material that is converted into the finished product. To process milk or make butter and other dairy products we require steam, chilled water, refrigeration system,maintenance of machinery and equipments. The departments, which are providing these services, are known as service departments. Service departments provide services to production departments and some service departments in addition to it also provide services to other service departments.

Assignment of Direct Costs to Departments and Products

The direct costs of accomplishing an activity or producing or distributing a product generally are routinely charged to that activity or product by the company’s accounting system. For example, direct labour would be charged to a product if only single product is produced. However if more products are manufactured in a department, the time spent in manufacturing a particular product and its quantity produced is ascertained to work out direct labour cost. The process of estimating direct labour cost becomes easy if time cards for doing the job or activity are kept in the department. If no records of this type are maintained, time studies can be conducted and used to determine the average time that a unit or sub unit takes to process the product. Direct material costs also may be routinely charged to products.Where a department processes only one product, the average product direct cost can be determined by dividing the total amount of direct cost of the department by the number of units produced (adjusted for work- in- process)

Allocation and Apportionment of Overhead (Primary Distribution)

The major problem arises when we are to decide how overheads ought to be allocated or apportioned among products in a multi-product firm or when joint products are produced what method should be adopted? This necessity arises as we are to consider the indirect costs’ share that should go to the product in its manufacturing. In addition there is the problem of joint costs involved in some
processes. How to account for such costs are some of the other relevant points.The theory of cost accounting suggests that the basis of the apportionment of overheads to the cost center should be on equitable basis. The procedure adopted for the distribution of overheads involves the following steps.

(i) Classification and collection of overhead.

(ii) Allocation and apportionment of overhead to production departments and service
departments

(iii) Re-apportionment of service department costs to production departments.

(iv) Absorption of overhead of each production department in cost units.

(i) Classification and Collection of Overhead

overheads need to be collected from various sources like i)Invoice ii)Stores requisitions iii)Wages Analysis Sheet and iv)Journal entries and classifying them where they are occurring.

(ii) Allocation and Apportionment of Overhead (Primary Distribution)

There are certain expenses which can be allocated directly to different departments or cost centers or products since these costs can easily be identified and allocated to a cost centers. But some expenses cannot be allocated to a particular department. Such expenses require division and apportionment over two or more cost centers or cost units.Different products pass through a number of departments and receive benefits from them in varying degrees. A Product must bear an equitable portion of expenses relating to it. These expenses might have been incurred in various production and service departments. The process of assigning the expenses to departments is known as departmentalisation.

Principles of Apportionment

Apportionment of overhead to various production and service departments is based on the following principles:

1. Service or use. This is the most common principle of apportionment of overhead costs. It is based on the theory that greater the amount of service or benefit received by a department/product, the larger should be the share of the cost to be borne by that department/ product.

2. Survey method. This method is used for those overhead costs that are not directly related to departments and survey may be conducted to find out the share of overheads to the cost centre.

3. Ability-to-pay method. This is based on canon of taxation, which holds that those who have the largest income should bear the highest proportion of the tax burden.

(iii) Re-apportionment of Service Department Costs to Production Departments

Not all items of the factory overhead are amenable to direct allocation. While some items can wholly be allocated to specific departments of cost centers, there are certain expenses, which need to be apportioned amongst different departments on an equitable basis. Costs of service cost centers (Service departments) are apportioned to productive cost-centers (Production departments) on equitable basis The effort related transfer price method assigns service costs to a department or product according to the amount of effort incurred.

Bases of Apportionment


The following bases are most commonly employed for apportioning items of overheads expenses among production/service departments.

(iv) Absorption of Overheads of Each Production Department in cost Units.Absorption is the allotment of overhead to cost units, may be a product, or process or an activity. It is the charging of overhead to individual product or units.The amount of overhead allocated and apportioned to the production department is to be borne by all cost units pertaining to that department. This is known as overhead absorption. Terms such as ‘recovery’, ‘application’ are also used. For the purpose of absorption of overhead to individual jobs, process or products,overhead absorption rates are applied. The term ‘overhead rate’ refers to the rate at which the overheads are to be charged to different cost units. It may be in the form of a percentage or a rate per unit.It may be based on actual cost or on the basis of estimated cost. or a pre-determined overhead rate or a blanket overhead rate for the entire factory. The blanket rate is computed as follows

Blanket rate = (Total overheads for the factory)/Base for the factory

Blanket overhead rate should not be used except when output is uniform.Otherwise it will result in over-costing or under-costing of certain cost units.Multiple Rates also may be applied for each department, cost center etc. For instance, separate rates may be calculated for each of the these Production department, Service department, cost center , product, fixed overhead and variable overhead.

The following formula is used to calculate the multiple rates:

Overhead rate = (Overhead of department or cos t center)/Corresponding base

A good absorption rate possesses the following characteristics

1. It is convenient to use and involves minimum of paper work

2. It should be according to the nature of the product.

3. It is stable so that comparisons can be made and also be flexible enough to take note of changing conditions

4. It does not bring much difference between recovered overheads and actual overheads

Methods Of Absorption of Manufacturing Overhead

There are various methods of absorbing manufacturing overhead. These methods have their own merits and demerits.

The more common of these are:

1. Percentage of direct materials cost.

2. Percentage of direct labour cost.

3. Percentage of prime cost.

4. Direct labour hour rate.

5. Machine hour rate.

6. Combined machine hour and labour hour rate.

(i) Percentage of Direct Materials Cost:

In this method the cost of direct materials used in the manufacture of a product is used as the base in absorption of factory overheads. The overhead rate is calculated on the basis of the following formula:

Overhead rate = ((Factory overheads)/(Direct material cos t))× 100

(ii) Percentage of Direct Labour Cost:
In this method, overheads are charged as a percentage of the direct wages incurred on jobs. The formula for computing the percentage is as under:

Overhead rate =(Factory overheads)/(Direct wages or labour cost))× 100

For example, when factory overheads are Rs.200000 and Direct Labour Cost is Rs.100000

The percentage overhead rate = ((1000000)/(200000))× 100 = 20%

(iii) Percentage of Prime Cost:

Here direct material cost, direct labour cost and other direct expenses,being all the constituents of prime cost are taken for calculation of the percentage.

The formula is:

Percentage on prime cost =((Factory overheads/Pr ime cost))× 100

For example if factory overheads amount to Rs.200000 and the prime cost is Rs.2000000,

Prime cost percentage comes to =(200000/2000000)× 100 = 10%

(iv) Direct Labour Hour Rate

In this method, the overheads are charged to production on the basis of number of labour hours spent on every job. The formula is


Direct labour hour rate = (Factory overheads/Direct labour hours used for the period)

Thus if total manufacturing overheads for a period are Rs.400000 and number of direct labour hours is 10000, then the labour hour rate works out to be Rs.4/- (400000/10000=Rs4/-). If a job takes 50 hours, then overheads applied will be 50 ́4=Rs.200/-

(v) Machine Hour Rate. It is the cost of running a machine per hour

Machine hour rate =(Factoryoverheads/ Machinehours duringa given period)×100

(vi) Combined Machine Hour and Direct Labour Hour Rate

A combination of machine hour rate and direct labour rate (called as dual hour rate) could also be used in those departments where work is done both manually and on the machine.

Joint Costs: In dairy industry or a dairy factory joint products and by products are obtained from the same raw material. In such cases Joint Costs of facilities or services employed in the output of two or more simultaneously produced commodities are involved . These Joint Costs are Common Costs till the point of split off when joint products and by products are obtained. The methods of apportionment of Joint Costs are based on the following bases

(i) Market Value Bases: under this method joint cost allocations are made on the basis of sale prices of the products provided the products can readily be sold in the markets without further processing. However, if further processing is required to bring the product into saleable form, value additions during further processing are to be assessed and deducted from the sale value to arrive at the basis for the apportionment of joint cost among the products.

(ii) Physical Unit Bases: under this method the joint costs are allocated to individual products on some physical basis, viz weight, volume, or some other common unit used to measure output.

Methods of Absorption of Administrative Overheads
In comparison to production overheads, administrative overheads relatively constitute a small portion of the total cost. There is a popular view that these overheads should not be treated as part of the cost of production because these are the period costs and should be debited to the Cost of Sales Account wholly.The other viewpoint is that it should be apportioned between production and sales departments. In such a case administrative overheads get merged with production and selling and distribution overheads. For the purpose of absorption of these overheads a single overhead rate is computed by any of the following methods

1. Percentage of Works Cost: Administration overhead is generally absorbed as a percentage of works cost. It is computed as follows

Overhead rate =(Admn. Overhead/Works Cost)× 100

2. Percentage of Sales: In this method, Administration overheads are absorbed as a percentage of sales which can be worked out as under

Overhead rate =(Admn Overhead/Sales)×100

3. As a percentage of Conversion cost: This method is not common and is rarely used

Overhead rate = (Admn. Overhead/Conversion cos t )× 100

Methods of Absorption of Selling and Distribution Overhead 

Selling and Distribution overheads may be allocated directly where they can be  identified with specific products. Where they cannot be identified with particular products, they have to be apportioned on some suitable basis, which may be one of the following.

1. Rate per article: Under this method, the total costs are estimated and are divided by the quantity of sales. It gives the rate per article.
 
Rate per article =(Total sellingand distributi costs/Numberof units sold)

2. A Percentage on Sales: In this method on the basis of the previous year’sfigures, a percentage of selling and distribution overhead to the total sales is calculated and the same rate is applied to recover the overheads from the selling price.

3. A Percentage of Works Cost: A percentage of selling and distribution overheads to works cost is arrived at from past records. This percentage rate is applied for the absorption of selling and distribution overheads

Overhead rate =(Selling and distributi on overheads/Works Cost)× 100

An improvement in cost measurement has been made by introduction of Activity-Based Costing (ABC). It is generally used as a tool for planning and control.

ABC is an approach to solve the problems of traditional cost management systems.Traditionally cost accountants had arbitrarily added a broad percentage on to the direct costs to allow for the indirect costs. Direct labour and materials are relatively easy to trace directly to products, but it is more difficult to directly allocate indirect costs to products However as the percentages of overhead costs has risen, this technique became increasingly inaccurate because the indirect costs were not caused equally by all the products.

As a result these traditional costing systems are often unable to determine accurately the actual costs of production and the costs of related services. Consequently managers were making decisions based on inaccurate data especially where there are multiple products.
 
Activity-Based Costing (ABC) is a method allocating costs to products and services on more scientific basis. Instead of using broad arbitrary percentages to allocate costs, ABC seeks to identify cause and effect relationships to objectively assign costs. Once costs of the activities have been identified, the cost of each activity is attributed to each product to the extent that the product uses the activity. In this way ABC often identifies areas of high overhead costs per unit and so directs attention to finding ways to reduce the costs or to charge more for costly products.

Classification of Costs

A useful approach for understanding the various aspects of costs consists in examining alternative cost classification schemes. Generally, costs incurred by manufacturers are classified in different ways. Three of these that we come across frequently are

1. By objects of expenditure/nature of elements.

2. By programme (such as cost of Job No.1, No. 2 etc)

3. By responsibility center (condending & drying, packing)

Each classification serves a specific purpose. In this section we shall discuss the first one in detail

I. Cost classification by Objects of Expenditure/ Nature of Elements In this classification costs are recorded according to the factors upon which expenditure is incurred viz., material cost, wages (labour cost) and expenses

Material cost: The term material refers to all those commodities that are consumed in the process of manufacture. Materials can be further classified into direct materials and indirect materials.Direct materials are those whose consumption may be identified with specific production units. Direct materials usually become integral part of the finished product. Direct materials thus include:
 
All materials used in production are wholly consumed in the production processes.For example milk used in making products such as butter, ghee, cheese or Ice cream. Sugar used in Ice cream or colour used in flavoured dairy drink. The cost on those items shall form direct material cost. Component parts used in product. Any primary packing materials such as LDPE film for packing milk or ghee.

Indirect Material: All materials which are used for purposes ancillary to the business and which can not conveniently assigned to specific physical units are known as indirect materials. Furnace oil used for boiler, grease and oil for machines, hydrochloric acid and caustic soda for house keeping in dairy industry fall under the category of indirect materials.Material cost includes cost on direct materials and indirect materials.

Labour Cost: The cost of remuneration of the employees of an undertaking fall under this category. It includes wages, salaries, commission, bonuses etc paid to employees. As per the statistics during 2001-2002 there were 865 dairy factories functioning in the organized sector in India having 83623 employees. Their total emoluments stood at Rs. 825.87 crores for the period under consideration. These employees included workers, supervisory and managerial staff and other employees.Employees can be further bifurcated into direct labour and indirect labour and cost associated with them is known as Direct labour cost and the 
Indirect labour cost respectively.

Direct Labour Cost. The wages paid to workers who are directly engaged in converting raw materials into finished products come under this category. These wages can be conveniently identified with a particular product; job or process.Wages paid to a technicians manufacturing butter or ghee or skim milk powder is an example of direct labour cost.

Indirect Labour Cost: Labour employed for the purpose of carrying out tasks incidental to goods produced or services provided is called indirect labour or indirect wages. Indirect labour is not directly engaged in the production operations required for product manufacture but only to assist or help on production operations. Mechanics, boiler attendant watch & ward staff, supervisors,storekeepers are examples of indirect labour and cost on these employees constitute indirect labour cost.

Expenses

All costs other than material and labour fall under this category and are termed as expenses. Expenses may be direct or indirect.

1. Direct Expenses

These are the expenses, which can be identified with and allocated to cost centers or units. Direct expenses can be conveniently allocated to a particular job or product or unit of service. These are also known as chargeable expenses or productive expenses. Hire of special machinery for a particular contract, cost of special drawings, designs and layout, carriage paid for materials purchased for a specific job fall under this category.

2. Indirect Expenses

Expenses which cannot be charged to production directly and which are neither indirect materials nor indirect wages are known as indirect expenses. Rent rates and taxes, insurance, depreciation, repairs and maintenance, power, lighting and
heating are few examples of indirect expenses.
 
The following chart shows the elements of cost mentioned above.

Overheads: Overhead costs are the indirect costs simply referred to as overhead. These cannot be directly attributed to any particular cost unit. The determination of overhead that should be properly associated with a given product is more difficult. It is because overhead costs cannot be identified with individual cost units and there are no accounting means of its exact distribution. Moreover they are generally not assumed to be directly associated with a department or product,either because there is no obvious relationship or because the cost of analysis and record keeping is considered too great.

There are three types of overheads.

1. Factory Overhead: Factory overhead includes all indirect expenses, which are incurred in connection with the manufacture of a product. They are also known as works overheads or factory burden or manufacturing overheads.Salary of plant manager and fee paid to Directors for guidance to solve production problems. Salary and other benefits paid to the Foremen, Timekeeper, Store Keepers and clerical staff of the factory,Cost of consumable stores,. Materials of small value such as cotton waste, small tools etc Rent, municipal taxes, depreciation, insurance etc., of the factory land and building,insurance, depreciation etc. of the factory plant, machineries, and equipment Factory lighting, heating and air conditioning, power and fuel (furnace oil, coal,gas, electric, etc.)Canteen and welfare expenses, telephone charges.Cost of training new employees, cost of experiment and research work.Cost of designing for production and drawing office expenses.Factory overheads may be fixed or variable.Fixed factory overhead are those costs, which do not vary with the volume of production. Examples are rent on factory building, insurance charges, property taxes, depreciation and supervisory salaries.
 
Variable factory overhead vary directly with the level of production. They include cost of fuel and power, repair and maintenance, cost of supplies and most indirect labour.

2. Administrative Overhead: It includes all those indirect expenses, which are incurred in general administrative and management function of an enterprise.
These overheads are of general character and are incurred for the business as a whole. Like factory overheads, administrative overheads tend to be fixed and variable.

The usual items generally included in these overheads are Salaries to Managing Directors, Directors, Executives and their staff, fees of Directors.

Office rent and rates and repairs and depreciation of office premises, power required for office equipment Audit fees, legal charges etc.

Stationary, postage, telephone charges, lighting and heating expenses and other utilities.

3. Selling and Distribution Overhead: Selling expenses are expenses of seeking to create and stimulate demand and of securing orders. Distribution expenses are expenses incurred in moving the goods from the company’s go downs to the customers’ premises. Selling and distribution expenses form no part of the cost of production but they take a considerable proportion of the price of the product.

The usual items included in selling and distribution expenses are :

Fee of Sales Directors, salaries of the Sales Manager and his staff including his office staff and his salesmen.

Traveling expenses and commission payable to salesmen.

Advertising and showroom expenses including rent and lighting.

Printing of catalogues and price lists and general stationary.

Rent of finished goods go downs and their repairs, etc.

Packing and carriage outwards, insurance in transit..

Depreciation, repairs and running expenses of delivery vans.

Telephone and postage etc. of sales department. Subscriptions to different agencies and trade journals.

Bad debts, legal charges for recovery of debts.

Having known classification of cost by elements of expenditure we can now derive various other costs.

The total of the Direct Expenditure comprising of Direct Materials, Direct Labour and Direct Expenses ——is known as Prime Cost or Flat Cost.

Prime cost plus Works or Factory Expenses is known as Works Cost or Manufacturing Cost or Factory Cost.
Product Costing

Works Cost plus Office and Administrative Cost is called Gross or Office Cost or Cost of Production.

Cost of Production plus Selling and Distributive Expenses is known as Cost of Sales. This differs from Selling price. Selling Price is equal to Cost of Sales plus Net Profit (or minus loss).

Methods of Costing

The methods of analyzing and presenting the cost vary from industry to industry.However, the basic principles of ascertaining costs are the same in every system of cost accounting.

1. Job Costing: Job costing is used where production is not repetitive and is done against orders. The work is usually carried out within the factory. Each job is treated as a distinct unit, and related costs are recorded separately.

2. Process Costing: Where an article has to undergo distinct processes before completion, it is often desirable to find out the cost of that article at each process.A separate account for each process is opened and all expenditure is charged thereon. The cost of the product at each stage is, thus accounted for. The output of one process becomes the input to the next process. Hence, the process cost per unit in different processes is added to find out the total cost per unit at the end.

Types of Costing

Various techniques are applied for ascertaining costs. These techniques may be used for special purposes of control and policy in any business irrespective of the method of costing being used there. These techniques are briefly explained below

1. Standard Costing: Standard Costing is a system, which seeks to determine beforehand what should be the cost and then actual cost is compared. The Standard Cost is pre-determined based on technical estimates of material, labour and overhead for a selected period of time and for a prescribed set of working conditions. This is a very valuable technique to control the cost as actual cost is measured against the standard cost. The differences between actual costs and standard costs are analyzed to know the reasons for the deviations. To correct the differences, remedial measures are then taken.

2. Absorption Costing: The practice of charging all costs, both variable and fixed costs to all operations, processes or products is defined as absorption costing.It is also known as traditional costing. In this method costs are ascertained after these have been incurred. Although until recently this was the only technique employed by cost accountants but now a days it is considered to have limited application as it doesn’t help in exercising control over costs. However it is useful in submitting tenders preparation of job estimates etc.

3. Marginal Costing: According to this technique only the variable costs are considered in calculating the cost of the product while the fixed cost is treated as period cost and no attempt is made to allocate or apportion this cost to individual cost centres or cost units. However fixed costs are charged against the revenue of the period. The revenue arising from the excess of sales over variable costs is technically known as contribution. The Marginal Cost includes direct material,direct wages, direct expenses and variable overheads. This technique helps to study the effect of changes in volume on profit and also take policy decisions such as product pricing in times of competition, whether to make or buy, selection of product mix.

4. Differential Costing: The concept of differential cost is based on the fact that in the real world, it is not practicable to employ ‘factors for each unit of output separately as inputs lack perfect divisibility unlike marginal costing.Differential cost is the difference in total cost between two alternatives.Differential costs arise due to the change in product lines, addition of new product or introduction of a ‘new product, replacement of worn out plant and machinery replacement of old technique of production with a new one.Differential costing considers all the revenue and cost differences amongst the alternative courses of action to assist management in arriving at an appropriate decision.

5. Uniform Costing: It is the use of same costing principles and or practices by several undertakings for common cost control or comparison of costs. Uniform costing provides reliable data for making inter firm comparison of cost performance. It facilitates comparison of the cost of production and the production efficiency between one unit and another. The working of a uniform costing depends on the co-operation of constituents of the industry.

Basic Cost Concepts

Cost Objective: It may be defined as any activity for which a separate measurement of costs is desired.

Cost Unit: It is defined as a unit of quantity of product, service or time (or a combination of these) in relation to which costs may be ascertained or expressed.Choice of cost unit depends upon the nature of the product manufactured, methods of production and trade practices.

Average Cost: An average cost is the cost of a product unit computed by dividing total cost by the number of units produced.

Conversion Cost: Conversion cost is the cost of production excluding direct materials, but including wastage in the direct material. It is total of direct labour,direct expenses and works overheads.

Variable Cost: If a given cost changes in total in direct proportion to changes in an activity it is variable cost.

Fixed Cost: Fixed cost remains unchanged for a given time period despite fluctuations in activity

Cost Center: Cost center has been defined as a location, person or items of equipment (or group of these) for which costs may be ascertained and used for the purpose of cost control. Cost Centre is a segment of a plant or in some case an entire plant, which is treated as functional units for the purpose of applying process overhead.

Productive Cost Center: A Productive cost center is directly engaged in productive activity and may consist of similar items of equipments.

Service Cost Center: Service cost centres are those cost centres, which are not directly engaged in productive activities, but provide services to productive cost centres so that production work may be carried out.

Cost Accumulation: It is the collection of cost data in an organized way in an accounting system.

Profit Center: Different cost centers when taken into a group headed by an individual or manager, who will be fully responsible for all cost, revenues and profitabilities of operation, the group is known as profit center.

Product Costing

In our competitive world profitability, growth and survival are the key issues confronting any business organization. No enterprise can survive and grow unless it is profitable in the long run. Profit is the result of two forces- revenue and cost.Revenue is the product of selling price and volume of output i.e., selling price multiplied by output it can sell. Selling price is influenced by market forces and is generally beyond the control of management. Similarly how much the output of a firm can be sold is again dependent upon market structure, price structure,marketing mix of the enterprise and host of other factors like government policies
concerning tariffs and taxes etc. Moreover the information about demand conditions is bound to be scarce and difficult to obtain, the cost information is usually plentiful which should be made use of by the managers. The firm pursuing the goal of profit maximization should endeavor to reduce per unit cost of production. The reduction in cost can be accomplished when cost per unit is ascertained. Therefore,knowing your production cost is critical. In present day economic scenario, accurate costing and pricing are key to success. Accurate costing avoids or minimizes distortions in product costing that result from arbitrary allocations of various costs.Managers want product costs for guiding their decisions regarding pricing and product strategies.

Managers also want product cost for the purpose of inventory valuation and income determination.The product is the smallest unit for which profitability is calculated.Product Costing It aids in arriving at profitability of the various business segments of an organization thus providing its total picture.

Product costing is the process of tracking and studying all the various costs that are incurred by the firm on its products or we can say what it costs to make the product. But before product cost is ascertained and estimated it is more relevant to define cost and other terms frequently used in costing. Cost has different meanings, differing among accounting, economics and engineering. The traditional accounting definition of cost is limited to the amount expended to acquire an asset. A more general concept equates cost with any sacrifice, past or future. In this context cost represents the resources that have been or must sacrificed to attain a particular objective. The concept of cost is multifaceted. The cost concepts shall be more clear if the following basic terms are understood properly.

Approaches to Managing Working Capital

Generally two approaches are followed for the management of working capital :

(i) the conventional approach and (ii) operating cycle approach.

The Conventional Approach: In this approach, each individual component of working capital viz. cash, inventory, receivables, payables etc. are managed efficiently such that, neither there is shortage of funds nor there is accumulation of excess funds. Since the cash position of the forms is affected by the management of the other items of working capital, the basic strategies that can be employed for the management of cash are 

(i) efficient inventory management

(ii) speedy collection of accounts receivables and 

(iii) stretching accounts payment without affecting the credit of the firm. 

An efficient inventory management is one that provides maximum customers service at a minimum cost. The optimum level of inventory is decided on the basis of the trade-off between cost of keeping inventory and benefits from it. As you know that inventory of a firm comprises of various items like, different types of raw materials, semi-finished goods in various stages of production, finished goods etc., it is not necessary for the manager to exercise same degree of control on all the items of inventory. The items which are most costly and/or converted into cash relatively slowly require more control. Hence, in the inventory control process, the inventory items are classified into three categories on the basis of the cost involved according to A B C System of classification. The items included in group A involve the largest investment and C group consists of cheapest items. Therefore,most rigorous and intensive control is required for A group of inventories and C deserve minimum attention. B group stands mid-way. It deserves less attention according to A B C System of classification. The items included in group A involve the largest investment and C group consists of cheapest items. Therefore,most rigorous and intensive control is required for A group of inventories and C deserve minimum attention. B group stands mid-way. It deserves less attention than A but more than C.

For receivable management, the firm has to decide whether or not to extend credit to a customer, how much credit to extend, what should be period for which credit is given, procedure for collection, in case of default etc. Similarly, the extent to which you can stretch your accounts payable will depend upon the credit policy, credit terms and collection policy of the creditor. There is no fixed norm for each of the above questions. The decision of the firm will be guided by the general nature of business, business environment and risk taking ability of the entrepreneur.

The Operating Cycle Approach: Under this approach, the working capital is determined by the duration of the operating cycle and the operating expenses needed for completing the cycle. In other words, this approach views working capital is a function of the volume of operating expenses.

The operating cycle has five major stages, (I) expenditure for purchasing raw material, stores etc. (II) inputs inventory (III) process interval (IV) warehouse(storage) interval and (V) collection interval. The operating cycle maintains circular flow of working capital from stage one through stage five as shown in the figure below. An effective management of working capital is that in none of these stages there is shortage of working capital nor there is excess of it.

Sources of Financing Working Capital

After determining the level of working capital, as illustrated in the preceding section, a firm has to decide how it is to be financed. The sources of finance for working capital can be broadly divided into four categories

1. Trade credit

2. Bank credit

3. Internal financing

4. Issue of share capital or debenture

The first three sources of finances are available to any type of firm viz. single proprietorship/partnership firms, private/public limited company etc., but raising funds through public issue of share capital or debenture is an option that only a public limited company can resort to.

Trade credit is the primary source of working capital finance for Indian firms. It comprises mainly of obtaining raw material or goods on credit and short-term borrowings from trading partners.

Short term bank credit is another important source of working capital. To obtain short-term bank credit, working capital requirements have to be estimated by the borrowers and the banks are approached with the necessary supporting data.

The banks determine the maximum credit based on the margin requirements of the security offered against credit grant. For example, if the margin requirement of a particular item is 60%, the bank will be prepared to provide credit upto Rs.40 thousand against the security of an asset worth Rs.1lakh.Besides providing credit for short-term through loan, overdraft, purchasing and discounting bills and cash credit; banks also advance term loans for working capital.

With a view to financing additional working capital needs, issue of additional shares or floating of debentures is another way. The companies eligible to raise capital through this option are required to follow the guidelines issued by the Government in this regard. Also, most of such companies are listed in the stock exchange.

Measuring Working Capital

In the previous section we have discussed the factors that influence the quantum of working capital in a business enterprise. Now let us attempt to determine the amount of working capital that an enterprise, say, dairy plant, would need by taking up an illustration.

Illustration Objective: To determine the magnitude of working capital for a newly set up ghee manufacturing unit using given information:

a) The proforma cost sheet provides following particulars:

b) Annual Production is estimated to be 24,000 kgs.

c) Raw material, parts and components are expected to remain in stores for average period of two days.

d) Materials are in process on average one day and at 50% completion stage.

e) Finished goods remain in stock on average 30 days.

f) Credit allowed by suppliers is 30 days.

g) Credit allowed to debtors is 60 days. Half of the sales are likely to be on credit.

h) Average time lag in payment to labour is 15 days and 30 days in overhead & fuel expenses.

i) Assume that sales and production follow a consistent pattern.

j) 10% of the computed figure is kept for buffer cash and contingencies. Solution:

Working notes: (a) The yearly production is 24,000kg., half of the sales are on credit, therefore, 12,000 kg. are sold on credit and 12,000 kg. on cash.

(b) Amount locked up in stock of raw material = (Annual production x Unit raw material cost x period for which stock required)/No. of days in year.

(c) Work in process stock = {(Annual production x Unit raw material or labour or overhead cost x period for which stock required)/No. of days in year}x 50%(because work in progress is assumed to be at 50% completion stage).

(d) Cost of finished good = (Annual production x Unit cost of finished good x period for which stock held)/No. of days in year.

(e) Debtors = (Credit sales x Selling Price x period of credit)/No. of days in year.

(f) Creditors for purchase of raw material = (Annual production x Unit raw material cost x period for which credit available)/No. of days in year.

(g) Av. lag in payment of labour = (Annual production x Unit labour cost x lag period for payment)/No. of days in year.

(h) Av. lag in payment of overhead = (Annual production x Unit overhead cost x lag period for payment)/No. of days in year.

Statement showing determination of net working capital.

Factors Determining Working Capital

The amount of working capital that a firm would need is affected both, by the endogenous and exogenous factors. The endogenous factors are associated with the firm itself while the exogenous factors are attributable to economic,monetary and general business environment. Among the various factors, the following are important ones:

i.Endogenous Factors

Nature and Size of business: Enterprises fall into some broad categories depending on the nature of their business. For instance, a dairy farm engaged only in producing dairy products is a manufacturing firm while one engaged only in selling the products is a trading firm. The working capital requirements of an enterprise are basically related to the conduct of the business. The manufacturing firms have to invest substantially in working capital for purchasing raw material, paying wages and salaries, incurring expenses on fuel and power etc. The working capital requirement of dairy products manufacturer increases, if his firm is a manufacturing-cum-trading firm. In that case, besides manufacturing expenses, firm must incur marketing and sales expenses on items such as advertising, opening retail outlets,commission to sales agents etc. The working capital needs of solely trading dairyconcerns fall between the requirements of manufacturing firms and manufacturing-cum-trading firms. This is so because the shelf life of dairy products is short and hence trading firm does not carry large stock of the same. The size o  business also has an important impact on its working capital needs. Size may be measured in terms of the scale of operations. A firm with larger scale of operations will need more working capital than a small firm.

Production Cycle: The production cycle starts with the purchase of raw materials and is completed with the production of finished goods. If the manufacturing cycle involves a longer period, the need for working capital will be more, because an extended manufacturing time span means a larger tie-up of funds in inventories.For instance, the working capital need for manufacturing cheese is higher than that pasteurization of milk due to longer time required for manufacturing cheese. Besides,the normal length of the production cycle, the working capital requirement is also affected by any delays in the manufacturing process. A delay at any stage results in accumulation of work-in-process, thus enhancing the requirement of working capital.

Production Policy: In the case of certain lines of business, the demand for products is seasonal, for example, ice-cream will be purchased largely during summer season. If a firm follows a steady production policy, that is, continues to manufacture the product during off-season also, then there will be large accumulation of finished goods (inventories) during the off-season. The progressive accumulation of stock will naturally require an increasing amount of working capital which will remain tied-up till sales pick up during peak season.

However, it is not necessary that all firms follow a steady production policy. Firms whose physical facilities can be utilized for manufacturing a variety of products can have the advantage of diversified activities. Such firms manufacture a few products throughout the year, while certain other products are manufactured only in specific season e.g., a dairy plant, producing pasteurized milk throughout the year, produces ice-cream also in summers. Thus, production policies may differ from firm to firm depending upon the circumstances. Accordingly, the need for working capital will also vary.

Operating Efficiency: Operating efficiency means optimum utilization of resources by eliminating waste, improving co-ordination and a fuller utilization of existing resources etc. Management can contribute to a sound working capital position through efficiency of operations that increases the working capital turnover.

Credit Terms: You must have observed that not all the sales of a firm are cash sales, but often firms sell goods to its customers on credit. If the firm offers liberal credit terms to its customers, its working capital in form of receivables increases.A long collection period will generally mean tying of larger funds in debts and may even increase the chances of non-receipts of the money due (bad debts).

Though the credit terms granted to customers, largely depend upon the prevailing trade practices and changing economic conditions, yet it may be treated as an endogenous factor within the control of the firm. On the other hand, the credit terms available to the firm from its creditors is a exogenous factor affecting the working capital requirement of the firm. A firm enjoying liberal credit terms will need less working capital. The other exogenous factors influencing working capital needs are discussed as under.

ii. Exogenous Factors
Business Cycle: Business expands during periods of prosperity and declines during the period of depression. An upward swing in the economy during periods of prosperity leads to increased sales and hence higher working capital requirement to meet the greater demand for its product. The downswing phase of the business cycle will have exactly an opposite effect on the level of working capital requirements.

Price Level Changes: A general rise in the price level leads to higher requirement of working capital for carrying out existing level of business activity. However, in cases where firm increases the price of the product in proportion to general increase in price level, the working capital needs remain more or less unchanged.

Other Factors : There are some other factors like profit level, tax rates, dividend policy and depreciation policy which affect the working capital of a firm. Higher net profits contribute positively to working capital while higher tax rate decreases working capital. Similarly, a firm’s policy of paying higher dividends to its shareholders means decrease in cash available with the firm and thus reduces the firm’s working capital to that extent.

Importance of Working Capital Management

It must be amply evident to us by now, that working capital has close relationship with day-to-day operations of a business. Inefficient working capital management may cause either shortage or excessive working capital; each of such situations is working capital is inadequate, a company faces the following problems:

- A company shall find it difficult to take advantage of profitable business opportunities due to shortage of funds.

- It is not possible for it to utilize production facilities fully and consequently thefirm’s profit goals shall not be achieved.

- A company shall not be able to take advantage of cash discount facilities.

- The credit-worthiness of the company shall be adversely affected, that is, the firm loses its reputation when it is not in a position to honour its short-term obligations.

- Fixed assets shall not be efficiently utilized due to lack of working fund for routine repairs and maintenance.

Too much working capital is as dangerous as too little of it. Excessive working capital raises the following problems:

- Excessive working capital in the form of very big inventories, increases the chances of inventory mishandling, waste and theft.

- It may lead to firms selling large quantity of goods on credit causing higher chances that more amount of money will be lost in form of bad debts.

- The company shall suffer from low profitability as its working capital is either not invested or is invested in low interest bearing securities.

Thus, we see that working capital management is like a tug-of-war between liquidity and profitability. A successful entrepreneur/manager, therefore, should keep the right balance between liquidity and profitability by maintaining the right amount of working capital on a continuous basis.

Concepts and Need of Working Capital

i.Concepts: There are two concepts of working capital; namely, Gross concept and net concept.

Gross Working Capital: According to this concept, working capital represents the total of all current assets. In other words, this concept views working capital and aggregate of current assets as two interchangeable terms. Working capital so defined is also referred to as ‘current capital’ or ‘circulating capital’.

This concept has the following advantages :
  •  Management is profoundly concerned with total current assets as they indicate the total funds available for operating purposes.
  •  It enables a firm to plan the use of funds for maximizing the returns to the enterprises.
Net Working Capital : The net working capital (NWC) is commonly defined as the difference between current assets and current liabilities. NWC is positive when current assets exceed current liabilities and it is negative when current liabilities are greater that current assets. From the point of view of working capital management, this is very important concept, as, to meet the contingencies in business, it is the excess of current assets over current liabilities which can be relied upon.

The concept of NWC is used to assess the liquidity position of the firm. The liquidity of a business firm is measured by its ability to satisfy short-term obligations as they become due. The greater the amount of NWC, the greater is the liquidity of the firm. Efficient working capital management seeks to ensure that an enterprise has sufficient NWC in order to be able to meet the claims of the creditors and other day-to-day needs of business. The amount of NWC that can be considered ‘sufficient’ vary from firm to firm and depends on a number of factors that we will discuss later.

The gross and net concepts of working capital are two important facets of working capital management. Both the concepts have operational significance for the management. The gross concept emphasizes the quantitative aspect while the net concept focuses on the qualitative aspect.

ii. Need for WC : The aim of the firm is to maximize the wealth of share-holders.For this purpose, firms should earn profits from its business operations. The extent to which profits can be earned will naturally depend upon the magnitude of the sales, among other things. To sustain, a successful sales activity sufficient working capital is necessary.

You are aware that a firm will be able to meet the customer’s demand for its product only if it has finished goods in stock, that is, firms must have adequate inventory to guard against the possibility of not being able to meet a demand for their products. Adequate inventory, therefore, provides a cushion against being out of stock. In several instances, sales of firms do not convert into cash instantly;there is a time-lag between the sale of goods and the receipt of cash. This is particularly the case for sale of goods by a manufacturing firm to the wholesaler and also by wholesaler to retailer, as they often sell goods on credit, in a desire to increase their business activity. Thus, to remain competitive necessitates the holding of accounts receivables.

A manufacturing firm needs to maintain additional liquidity to meet the expenditure on several items, like raw material, fuel, power, wages, salaries etc. in the process of manufacturing the goods. Even if a business concern does not manufacture goods on its own, rather it purchases it from manufacturer or wholesaler, working capital in the form of cash is required to meet its routine requirement to finance the transactions which a firm carries out in its ordinary course of business. This is called transactions motive of requiring cash balances.

Besides transactions motive the firms need working capital in the form of cash in hand or bank for three other purposes, precautionary motive, speculative motive and compensation motive. Precautionary motive refers to the need of keeping cash balances in reserve for random and unforeseen circumstances e.g. strike,failure of important customers, cancellation of order etc.Speculative motive refers to the desire of a firm to take advantage of opportunities which present themselves at unexpected moments and which are typically outside the normal course of business. For example, an opportunity to purchase raw materials at a reduced price on payment of immediate cash; a chance to speculate on interest rate movements by buying securities when interest rates are expected to decline etc. While the precautionary motive is defensive in nature in that, firms must make provisions to tide over expected contingencies, the speculative motive represents a positive and aggressive approach.

Compensation motive to hold cash balances is for compensating the banks for providing certain services to business firms like clearance of cheque, supply of credit information, transfer of funds etc. You may be knowing that for some services, like making bank drafts, banks cheque, a commission or fee, is there but do you know that for several other services, banks seek indirect compensation?Let us tell you how banks do this. Usually, clients are required to maintain a minimum balance of cash at the bank. Since this balance cannot be utilized by the firms for transactions purposes, the banks themselves can use the amount to earn a return. To be compensated for their services indirectly in this form, they require the clients to always keep a bank balance sufficient to earn a return equal to the cost of services. Such balances are compensating balances.

Accounting and Working Capital Management

In the previous section, we read about the usefulness of maintaining accounts for understanding and taking stock of the organisation’s performance in order to carry out a SWOT (strength, weaknesses, opportunities and threat) analysis of organisation and make appropriate decision for the growth of the enterprise. In this section, we shall focus specifically on the role of accounting for working capital management.

We will hardly find a running business firm that does not require working capital.Since working capital is pre-requisite for a business enterprise, its management is an integral part of the overall corporate management. The goal of working capital management is to manage the firm’s current assets and current liabilities in such a way that a satisfactory level of working capital is maintained.We have already learned in Unit 5, what are current assets and current liabilities.

To refresh our memory, let us define the same again. The term current assets refers to those assets which in the ordinary course of business can be, or will be,turned into cash within one year without undergoing a decrease in value and without disrupting the operations of a firm. The major current assets are cash, marketable securities, accounts receivable and inventory. Current liabilities are those liabilities that are intended at their inception to be paid in the ordinary course of business, within a year, out of the current assets, or earning of the business. The basic current liabilities are accounts payable, bills payable, bank over-draft and outstanding expenses.

The information on each of these items of current assets and liabilities, sources and uses of working capital is contained in accounting statements. These statements provide an insight to the management on the following questions:
  •  What is the magnitude of current assets, current liabilities and hence working capital?
  •  What are the items causing changes in current assets and liabilities?
  •  What are the various sources of working capital and how they have changed over the years?
  •  To what uses the working capital has been put to?
A precise answer to the above questions in quantitative terms is the key to efficient management of working capital. Since accounting statements provide this information, undoubtedly, accounting is an essential input for working capital management.

Purposes of Accounting Information

Much of the modern business management has been made possible only by
a counting information. Management is a process of converting information into
action; and accounting is a source of most of the information that is used for this
purpose.

We have already learned in the previous Unit that in accounting process, financial information i.e. information involving money matters of a business enterprise, is recorded, classified and summarized. These data on various transactions of the business entity are classified into different heads like revenue, expenditure, current assets, current liabilities, owner’s equity, fixed assets, long-term liabilities etc.
 
The classification and presentation of the data in this way enables any interested
person (manager, shareholder, creditor etc.) to analyse it for understanding and
taking stock of the organisation’s performance. This draws the attention of the
user of accounting information to take a decision. For example, the annual financial report of the company can be used by the shareholders, to assess the actual performance of the company vis-à-vis their expectations, and hence make their future investment decisions accordingly.
 
Let us take another example, where the accounting information reports a fall in
net profit of a dairy plant this year in relation to previous year’s profit and/or profits of other dairy plants. This will immediately focus the attention of manager towards the need to arrest the decline in profit and trigger a whole series of actions in this direction like evaluation of reasons for the decrease in profits, remedial decision to be taken and so on. Thus, in nutshell, accounting information serves the purpose of focusing a manager’s attention on operational deficiencies,weaknesses, the threats and opportunities of a business enterprise.
 
The role of accounting does not stop at attention directing but goes further to
enable quantification of the different alternative solutions and their relative merits and demerits. For instance, the manager in our previous example can evaluate the alternative solutions to increase profits, like, drop least profitable product line, decrease administrative expenses, increase sales revenue etc., by quantifying the effect of each of the alternatives on profits using the accounting information.

Thus, important purposes of accounting information can be summarized as keeping score of the organizations performance, attention directing of users of the information and problem solving for growth of enterprise.

Maintenance of Accounts and working Capital Management

You have learned in Unit 5 that, various branches of accounting cater to the information needs of various users such as shareholders, auditors, management,
employees etc. But, when we talk about ‘accounting information’, we generally
look at it in a broad sense, rather than in terms of its specific branches like financial accounting, management accounting, cost accounting etc. In this Unit, we shall deal with some illustrative uses of accounting information for the purpose of management of funds in the short-term, that is, for current operations of the business.
 
The term ‘funds’ here refer to working capital (WC), which can be regarded as that portion of the firm’s total capital, which is employed in short-term operation.In simple words, we can say that WC is the investment needed for carrying out day-to-day operations of the business smoothly. The management of WC is equally important as the management of long-term financial investments in a business.But before, we explain the significance of WC & approaches for its efficient management; let us take a brief look at the purpose of accounting information in general, and its role in WC management, in particular.

Single and Double Entry System

There are basically two approaches of record keeping

i) Single Entry Systems and

ii) Double Entry Accounting Systems

Single Entry Systems: The term ‘Single Entry Book Keeping’ is generally applied to any system which is not a complete double entry system. Single entry systems of keeping books differ in the amount of detail and information concerning the business but all such systems have one common feature, viz. incompleteness of double entry.There is so much variation in ‘Single entry system’ of keeping records that in case of some of the transactions, no entries may be made; in others a single entry to record only one side of the transaction may be made while the two fold aspect of each transaction as considered in the double entry system is ignored.However in some other transactions a complete double entry may be made.Methods of record keeping in single entry system is quite different from the double entry system and also information is usually available up to a point. The original records such as the cash book, the purchase book, the sale book and returns book, and the bill book are sometimes maintained but postings are only made to the personal accounts concerned. It fails to give information of the impersonal side of a transaction and lays more emphasis in recording the personal side.

Single Entry system of record keeping fails to supply details regarding expenses,purchases and sale of goods as well as cost of assets such as plant and machinery,fixture and fittings and other real and nominal accounts. Thus at any stage when data are required in different aspects single entry system can only furnish a list of Debtors and Creditors along with amount outstanding. In the Single Entry System only final statements (not final accounts) can be drawn up;It may not, however, be concluded from the above discussion that owing to an incomplete record of transactions, it is not possible to determine Profit and Loss for the period. It is possible to draw up a statement of profit & loss showing the difference between the assets and the liabilities at the terminal periods, and a
statement of affairs showing the assets and liabilities on the two sides of the statement on a particular date. In both the statements it may be necessary in appropriate cases to make some adjustments.

The profit and loss is ascertained by comparing the capital at the end with that at the beginning, adjustments being effected in respect of withdrawals or introductions of capital during the period. The withdrawals must be added and introduction of capital be deducted to ascertain the profit or loss. If the closing capital is more than the opening capital such excess is considered as profit for the period. But if the closing capital is less than the capital at the beginning, there is loss for the period, subject to adjustments mentioned above. Capital as considered for this purpose is the excess of assets over liabilities.The disadvantages of single entry system as compared to double entry are many.The arithmetic accuracy of the books cannot be proved, assets and liabilities may be wrongly shown, and the final statement of affairs cannot be relied upon.

The final results concerning the state of business are unreliable, owing to an incomplete record of transactions, lack and loss of information pertaining to the assets and particulars as to gains and losses. In such type of system a Trial Balance cannot be made from the records maintained. Profit determination in these circumstances can be extremely difficult. However many short -cuts are
employed as a means to complete the double entry depending upon the degree of completeness already existing in the books. This form of book keeping is of very limited value and is seldom found in the any concern of importance.

Double Entry Book Keeping

Double-entry book-keeping is the standard accounting practice for recording financial transactions. It is a system of accounts keeping wherein all the financial transactions of an enterprise are recorded in a manner to show the effect of each on the assets, the liabilities, the owner’s equity, the revenue items and the expense items

Double-entry book-keeping is governed by the accounting equation. At any point of time, the following equation must be true:

Assets = Liabilities + Equity

For a particular time period, the equation becomes:

Assets = Liabilities + Equity + (Revenue - Expenses)

Finally, this equation may be rearranged algebraically as follows:

Assets + Expenses = Liabilities + Equity + Revenue

This equation must be true, for any time period. If it is, then the accounts are said to be in balance. If the accounts are not in balance, an error has occurred. For the accounts to remain in balance, a change in one account must be matched with a change in another account(s). These changes are known as debits and credits.Note that the usage of these terms in accounting is not identical to their everyday usage.

Double entry book keeping recognizes the fact that each entry affects at least two accounts. This is the dual or double feature of this system. There cannot be a debit without a corresponding credit and vice versa.

The principle book of account is ledger in which all transactions are ultimately recorded in double entry system although a number of subsidiary books are also necessary. As already mentioned the ledger is a set of accounts of an enterprise.This means ledger comprises of accounts each account being devoted solely to transactions with a particular person or of a particular kind. Having learnt the basics of book keeping I am sure now you are in a position to record business events , present them and interpret.

We shall explain this with the help of an example.

Mr. Ram Singh started dairy business and the following information was obtained

April 1 – Started business with Rs. 30000

April 4- Bought goods with Rs. 20000

April10- Received order for half of the goods from ‘A’

April12- Delivered the goods, A invoiced Rs. 13000

April15- Received order for remaining half of the total goods purchased.

April 21-Delivered goods and received cash Rs. 120000

April 30- ‘A’ makes payment

April 30- Paid salaries Rs. 2100

April 30-Received interest Rs. 500

To understand how the entries are to be made in each account according to double entry system of book keeping, let us first analyse each transaction to see what are the accounts that are affected by each transaction.

April 1- Started business with Rs. 30000

The two accounts involved are cash and owners equity. Cash increases and being an asset it has to be debited. Owners’ equity, a liability also increases and therefore, it has to be credited.

April 4 –Bought goods worth Rs. 20000

The two accounts affected by this transition are Cash and Goods (purchases).Cash balance decreases and hence it is credited and goods on hand, an asset,increases hence it is to be debited.

April 10- Received order for half of goods from ‘A’No entry is required as realization of revenue will take place only when goods are
delivered (Realisation concept).

April 12 – Delivered the goods, ‘A’ invoiced Rs. 13000

This transaction affects two accounts – Goods (Sales) a/c and Receivables a/c.Since it is a credit transaction receivables increase (asset) and hence is to be debited. Sales decreases goods on hand and hence Goods (Sales) a/c is to be credited.

April 15 -Received order for remaining half of goods No entry is required as transaction is not complete.

April 21- Delivered goods and received cash Rs. 12000

This transaction affects cash a/c and sales a/c. Since cash is realized, the cash balance will increase and hence cash account is to be debited. Since the stock of goods becomes Nil due to sale, sales a/c to be credited (as asset in the form goods on hand has reduced due to sales).

April 30 - ‘A’ makes payment

Both the accounts affected by this transaction are assets accounts – cash and receivables. Cash balance increases and hence it is to be debited and receivables balance decreases and hence it is to be credited.

April 30- Paid Salaries Rs. 2100

Because of payment of salaries cash balance decreases and hence cash account is to be credited. Salary is an expense and since expenses has the effect of reducing owners’ equity account, expenses account is to be debited.

April 30- Received Interest Rs. 500

The receipt of interest increases cash balance and hence cash a/c is to be debited.Interest being revenue which has the effect of increasing the owners’ equity, it has to be credited as owners’ equity account increases.

 
The Cash Account and the Capital Account have been done here, you are advised to prepare similarly the other relevant Accounts.
 
Double entry system has the following advantages.

1. It provides a complete record of every transaction both in its personal and impersonal aspects.

2. Financial position of business at any movement can be ascertained with the help of balance sheet and profit & loss for any given period can be easily worked out.

3. It provides an arithmetical checks on the records. It , therefore ,reduces risk and facilitates the detection of errors and frauds.

4. From personal accounts the amount due to and by each person with whom the business deals can at any time be ascertained.

Accounts Their Construction

How accounts are made? What are sources of these accounts to initiate the accounting process so that the required statements are generated subsequently?What is the format of accounts and what purpose do they serve? Before we answer all these questions it is worthwhile to understand some of the frequently used terms in accounting.

i.Account

An Account is a systematic record of the financial transactions pertaining to a particular asset, a particular liability, an owner’s equity item, a revenue item or an expense item. Transactions of similar nature are brought together at one place in an account, which are opened in a book called Ledger.

ii. Ledger

A ledger is a set of accounts of an enterprise. It may be kept in bound or Loose Leaf form. All these accounts, each on a separate page or card are the source of information for preparation of the various financial statements.

iii. Journal

A journal is a chronological record of transactions. The Journal is the original book in which the transactions are recorded in the order in which they happen.

iv. Assets

Assets are items of value owned by a enterprise. It includes tangible and intangible items or rights. Tangible items may be in the form of money, buildings, machinery etc. Intangible items include claims on tangible assets, claims on services and also items such as goodwill, patents, copyrights and franchises. Assets can further be classified into current assets and long term assets.

v. Equities

These are claims against the enterprise. Claims are of two types

i) Liabilities: amount due to outsiders. Liabilities are debts or obligations of the enterprise to pay money or other assets at some future date. Liabilities can be further classified into current liabilities and long term liabilities

ii) Capital: Claims of owners or proprietors.

The sum of the claims of outsiders (creditors) and that of the owners is always equal to the total value of all assets owned by the enterprise. It is known as the Fundamental Accounting Equation.
 
Having known the basic terminology let us understand how an account is constructed. We know that accounting is concerned with the recording of financial transactions of a business entity. The source of account is a document (calledSource Document) which becomes the basis for recording a transaction in the books of accounts. Source documents are the original sources of information that provide documentation (proof) that a transaction has occurred. Sales invoices,invoices from suppliers, contracts, cheques written and cheques received, promissory notes, and various other types of business documents are source documents.These documents provide us with the information needed to record our financial transactions in our bookkeeping records.There is a variety of forms for accounts but the most common is the ‘T’ account because each account form resembles a capital letter ‘T’.The title is placed above and in the centre of each account At the centre of the horizontal line a perpendicular is drawn downward to separate the account into two distinct parts. The left part of the T account is called debit side and the right one is called the credit side as shown below:


To enter an amount on the left side of an account to known as debiting 

To enter an amount in the right side of an account is known as crediting the account.

The Rules of Debits and Credits and the Account How to determine whether an entry is to be made in debit or credit side of any account and what are the rules that guide us so that the proper entries are made in the book of accounts? The following shall help us in this process.

(1) Determine the type of account (asset, liability, revenue, or expense account) the transactions affect

(2) Determine if the transaction increases or decreases the account’s balance.

(3) Apply the debit and credit rules based on the type of account and whether the balance of the account will increase or decrease after the transaction.

Assets are increased by debits. There is no reason for this other than that it has been conventional approach for several hundred years. If an asset is increased by a debit and if debits must equal credits, then a liability account or stockholders’equity account must be increased by a credit Conversely assets are reduced by credits and debits would then reduce liability or stockholders’ equity. The following rules of making entries are adopted with respect to assets, liabilities and capital and the nominal accounts.

Regarding Assets: Increases in assets are debits and decreases in assets are credits.

Regarding Liabilities: Increases in liabilities are credits and decreases in liabilities are debits.
Regarding Capital: Increases in capital are credits and decreases are debits.

Regarding Expense: Increases in expenses are debits and decreases are credits Regarding Income or Profits: Increases in income or profit are credits, decreases are debits

Regarding Stocks: Debit what comes in and credit, what goes out.

Regarding Receiver/ Giver: Debit the receiver and credit the giver

The purpose of accounts is to supply the recorded data for the preparation of accounting statements.


Most Reading